

Greetings Roscom readers. For this autumns post, we have been through the interactive data made available by Ofcom online and we have pulled out the parts that we found the most interesting.
Monthly Spend
In 2016, the average UK monthly household spend on fixed voice and data was £53.93, with mobile voice and data at £65.46. Fast forward to 2025, and fixed voice and data is now averaging £43.82 and mobile voice and data are averaging £41.70. For fixed that is a drop of 18.75% and for mobile that is a drop of 36.30%.
Minutes Used
“Total fixed and mobile call volumes fell by 12 billion minutes (7%) to 164 billion minutes in 2025. Ninety-one percent of call minutes originated on mobile networks in 2025. However total outgoing call volumes from mobile phones decreased by 9 billion minutes (6%) to 149 billion minutes in 2025.”
Messages Used
“Use of SMS and MMS messaging continued to decrease in 2025, down by 6 billion messages (23%) to 22 billion messages. This decline is likely to be driven by growing use of over-the-top (OTT) messaging services such as WhatsApp, iMessage and Messenger.”
Comparatively in 2020, 48 billion SMS/MMS were sent.
Data Used
“Total mobile data consumption in 2025 was up by 14% to 11.7 exabytes. While post-pay data use rose by 13%, growth was faster in the pre-pay segment at 23%.”
Comparatively in 2020, total data consumption was 4.5 exabytes.
Revenue
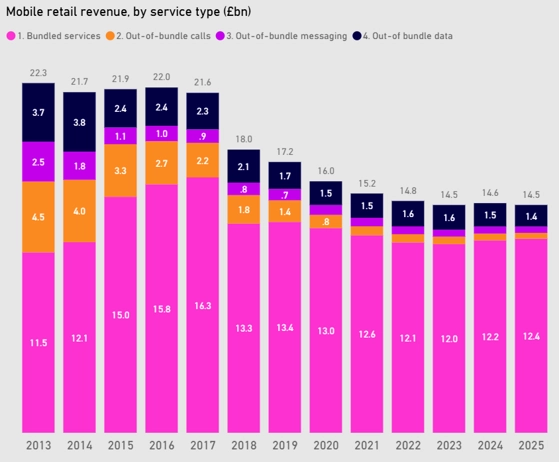
“In 2025, retail mobile telecoms generated £14.5bn in revenue, a £0.1bn (1%) decrease compared to 2024. Eighty-five percent of mobile revenue was generated by bundled services.”
Interestingly for 2025 out of bundle data made up £1.4bn out of the total £14.5 billion, while voice was only £0.4bn and messaging £0.4bn. So out of data bundle holds a lot of value still for mobile network operators, especially in the context of how little the overall revenue changed. As shown in the below image:
Pre-pay / Post-pay split
Of the 122.7 million subscribers in 2025, 100.6 million (81.99%) were post-pay and 22.1 million (18.01%) were pre-pay.
Summary
- Spend on communications overall is decreasing (due to the cost-of-living crisis and the ultimate commoditsation of telecom services)
- Voice and messaging usage is decreasing (due to OTT services increasing in popularity)
- Data contunes on the rise (as the data bundles get bigger, data speeds get faster [5G], and mobile applications/users require more and more data e.g. streaming)
These summaries may of course read as being quite obvious, but its only really when you start to look at the statistics that you begin to see the true impact to the UK market and how it is changing at a rapid pace.
What is next for 2026/27 – if you are familiar with UK TV adverts of recent months, its clear to see that satellite calling, 5GSA (5G standalone), UK operators offering ‘5G plus’ or similar advanced technologies are the drive. Some claiming to improve the battery life of a users phone… Meanwhile there are MVNO operators now offering ‘unlimited’ data bundles for as little as £9 a month (with fair usage capped policies).
Just what will come next? (there are certainly more satellites in the sky now…)
Source of all statistics, charts and quotes: https://www.ofcom.org.uk/phones-and-broadband/service-quality/communications-market-report-2026-interactive-data